First-Time Home Buyer GST Rebate Alberta: What You Save in 2026
First-Time Home Buyer GST Rebate in Alberta: What You Actually Save in 2026
If you're a first-time buyer building or buying new in the Edmonton area right now, the federal government will hand back up to $50,000 in GST once your purchase closes. That's not a rumor or a builder sales pitch. Bill C-4, which created the First-Time Home Buyers' GST Rebate, received Royal Assent on March 12, 2026, and the Canada Revenue Agency is processing claims right now (MNP, 2026).
Most of what's written about this rebate comes from builders promoting a specific show home, or national outlets writing with an Ontario or BC audience in mind, where the HST math looks different. This post is built around actual Edmonton-area numbers: what the rebate is worth on a new build in Laurel versus Keswick, why it does nothing for most Edmonton buyers who are shopping resale, and how it stacks with the FHSA and RRSP Home Buyers' Plan you might already be using for your down payment.
- First-time buyers get a full GST rebate, up to $50,000, on new homes priced at $1 million or less, with partial relief continuing up to $1.5 million (Canada Revenue Agency, 2026).
- The rebate only applies to newly built homes bought from a builder, an owner-built home, or co-op shares. Resale homes were never charged GST, so the rebate does not apply to them.
- On a $650,000 new build in Glenridding Ravine, the rebate is worth $32,500. On a $750,000 home in Keswick, it's $37,500.
- This replaces a much smaller rebate that capped out at $6,300 and disappeared entirely once a home passed $450,000.
- It stacks with the FHSA and RRSP Home Buyers' Plan. None of the three programs reduce what the others are worth to you.
What Is the First-Time Home Buyers' GST Rebate?
The First-Time Home Buyers' GST Rebate refunds 100% of the GST, or the federal portion of the HST, on a newly built home valued at $1 million or less, with a shrinking partial rebate for homes priced up to $1.5 million (Canada Revenue Agency, 2026). It applies to purchase agreements signed with a builder on or after March 20, 2025, and construction has to begin before 2031.
In Alberta, this math is simpler than it is for buyers in Ontario or BC. Alberta charges no provincial sales tax and no HST, just the flat 5% federal GST. So the rebate calculation here is one number, not a blended provincial-and-federal rate. That's a real, if small, advantage for Alberta buyers working through this compared to buyers doing the same math in Toronto or Vancouver.
How Much Does It Actually Save You on an Edmonton-Area New Build?
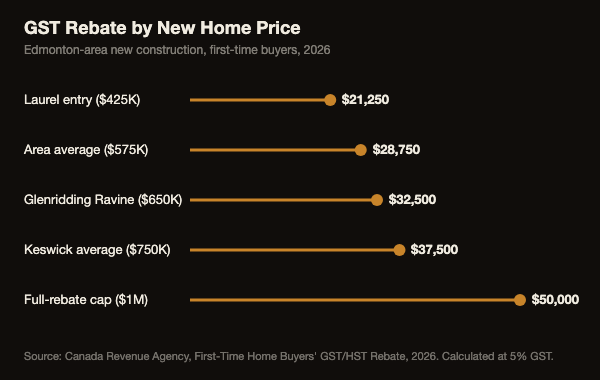
The math is simple: multiply the home's pre-tax price by 5%. On a $575,000 new build near the Laurel average, that's $28,750 back. On a $750,000 home priced closer to Keswick's average, it's $37,500. Neither of those is a rough guess. It's the GST rate applied directly to real Edmonton-area new-construction pricing.
Here's what that looks like across the price points first-time buyers are actually seeing in Edmonton's newer southwest and southeast communities right now.
| Community / Price Point | Typical New Build Price | GST Rebate at 5% |
|---|---|---|
| Laurel, entry single-family | $425,000 | $21,250 |
| Laurel, area average | $575,000 | $28,750 |
| Glenridding Ravine, detached | $650,000 | $32,500 |
| Keswick, average listing | $750,000 | $37,500 |
| Full-rebate cap | $1,000,000 | $50,000 |
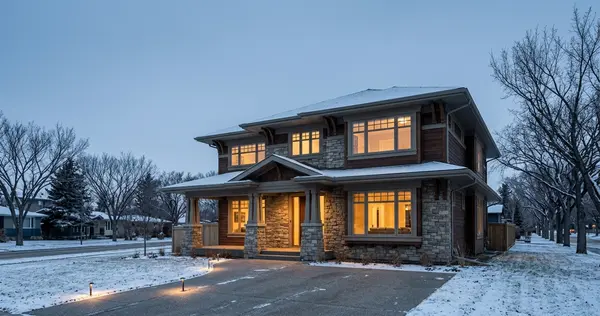
Single-family homes in Laurel start in the low $400,000s, which is exactly the kind of price point this rebate was built for. Buyers there and in Glenridding Ravine are looking at $20,000 to $30,000 back, real money that used to just disappear into the purchase price.
Who Actually Qualifies in Alberta?
You qualify if you're at least 18, a Canadian citizen or permanent resident, and buying as an individual rather than through a corporation or partnership (Canada Revenue Agency, 2026). The bigger test is the "first-time" part: you and your spouse or common-law partner can't have owned and lived in a home, in Canada or anywhere else, during the current calendar year or any of the four calendar years before it.
- Age and residency: 18 years or older, Canadian citizen or permanent resident.
- Ownership history: Neither you nor your spouse or common-law partner lived in a home either of you owned in the current year or the previous four years.
- Buyer type: Individuals only. Corporations and partnerships are not eligible, even if a person is the sole shareholder.
- Property use: The home has to be intended as your primary place of residence, not a rental or investment property.
That four-year lookback catches more people than you'd think. If you sold a home in Edmonton three years ago and have been renting since, you still don't qualify as first-time under this program, even though it might feel like you're starting over.
Why This Doesn't Help Most Edmonton Buyers (Resale Is Already GST-Free)
Most Edmonton buyers won't see a penny of this rebate, because most of Edmonton's market is resale, and resale homes have never been subject to GST in the first place. If you're shopping in Terwillegar, Windermere, or almost any established neighbourhood on the resale side of the market, this program has nothing to offer you. There's no GST sitting on that purchase to rebate.
Nationally, only about 5.8% of new home buyers qualify as first-time purchasers under this program (Canadian Home Builders' Association, 2026). That's a narrow slice of an already narrow slice: new construction buyers who also happen to be buying their first home. I bring this up because a lot of buyers hear "$50,000 rebate" and assume it applies to whatever they're looking at. It doesn't, unless you're specifically buying new from a builder.
Old Rebate vs. New Rebate: What Changed
The GST/HST New Housing Rebate already existed before this. It capped out at $6,300 and phased down to nothing once a home's price passed $450,000 (Canada Revenue Agency, 2026). Most Edmonton-area new builds, at $500,000 and up, got little or nothing from that older program.
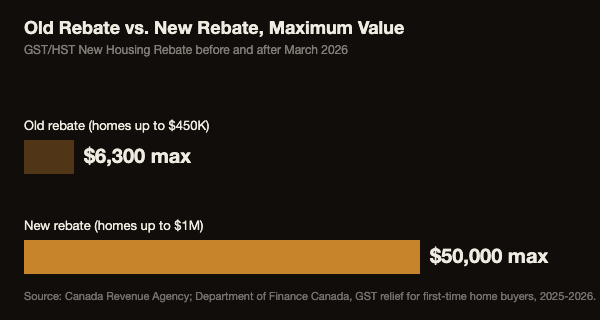
The new First-Time Home Buyers' GST Rebate is a completely different scale. It's not an adjustment to the old program, it's an eight-fold jump in the maximum benefit and a more than doubled price ceiling. A first-time buyer can technically qualify for both rebates on the same purchase, but the new program is the one doing almost all of the work on anything priced above $450,000.
How You Actually Get the Money: Builder Credit or CRA Claim
Most builders credit the rebate directly into your purchase price at closing, so you never have to front the GST and wait to get it back (Mortgages for Less, 2026). Some builders handle the paperwork on your behalf. Others expect you to apply directly to the CRA after closing, usually through a CRA My Account, with proof of your purchase agreement and occupancy.
If your ownership transfer happened before Royal Assent on March 12, 2026, you don't automatically get the rebate. You have to apply to the CRA separately, and you generally have a two-year window from closing to do it. Ask your builder in writing, before you sign anything, whether they're crediting the rebate at closing or leaving it to you to claim.

Stacking the GST Rebate With Your FHSA and RRSP Home Buyers' Plan
The GST rebate does not reduce what your FHSA or RRSP Home Buyers' Plan is worth, and neither of those programs reduces the GST rebate. They solve different problems. The FHSA and RRSP HBP help you build the down payment before you ever get to closing. The GST rebate reduces the amount owed on the purchase itself, usually applied right at closing rather than something you wait months for.
I walked through the FHSA and RRSP HBP combination in detail in a separate post, including how much a couple can realistically stack toward a down payment using both accounts (FHSA + RRSP HBP Combined). If you're buying new construction as a first-time buyer, that down payment strategy and this GST rebate are two separate levers on the same purchase, not competing programs you have to choose between.
My Take: Does This Change the New vs. Resale Decision Right Now?
In my opinion, this rebate matters more this fall than it would have a year ago, because it's landing at the same time Edmonton's market has cooled. Builders in communities like Keswick and Glenridding Ravine are already offering incentives to move inventory as listings pile up (see my breakdown of Edmonton's market cooldown). Stack a builder incentive on top of a $30,000-plus GST rebate, and new construction starts to pencil out a lot closer to resale than it did even 18 months ago.
That said, I still walk most first-time clients through the resale side first. New builds carry timeline risk, deposit structures are different from a resale condition period, and the rebate only applies if the home is genuinely your primary residence. It's a real number, not a reason to buy new on its own. Isn't the smarter move to run both scenarios with real numbers before deciding? That's the conversation I'd rather have before you sign anything.
Trying to figure out if a new build actually pencils out for you?
The Edmonton Budget Buyer's Guide breaks down what different price points buy across the city, new and resale, or we can run your specific numbers together.
Get the Budget Buyer's GuideFrequently Asked Questions
Does the GST rebate apply to resale homes in Edmonton?
No. Resale homes have never been subject to GST, so there's nothing to rebate. The First-Time Home Buyers' GST Rebate only applies to newly built homes bought from a builder, owner-built homes, or new co-op housing shares (Canada Revenue Agency, 2026).
How much is the GST rebate worth on a $600,000 new home?
On a $600,000 new build, the full GST rebate is worth $30,000, since 5% of $600,000 is $30,000 and the home falls well under the $1 million full-rebate threshold (Canada Revenue Agency, First-Time Home Buyers' GST/HST Rebate, 2026).
Do I have to apply for the GST rebate myself?
It depends on the builder. Many builders credit the rebate directly into the purchase price at closing and handle the CRA paperwork themselves. If yours doesn't, you generally have up to two years from closing to apply directly to the CRA (Mortgages for Less, 2026).
Can I use the GST rebate together with my FHSA and RRSP Home Buyers' Plan?
Yes. The GST rebate reduces what you owe on the purchase itself, while the FHSA and RRSP Home Buyers' Plan help fund your down payment beforehand. None of the three programs reduce what the others are worth to you.
What happens if my new home costs more than $1 million?
Homes priced between $1 million and $1.5 million get a partial rebate that shrinks as the price rises, and homes at $1.5 million or above get nothing (Canada Revenue Agency, 2026). Most Edmonton-area new construction falls well under the full $1 million threshold.
None of this requires guessing. The rebate rules are published, the math is a flat 5% calculation, and Edmonton-area new-build pricing is public information. If you're a first-time buyer weighing new construction against resale this fall, run the actual numbers on the specific home you're looking at rather than going off a headline "$50,000" figure that may not apply to your price point at all.
Categories
Recent Posts